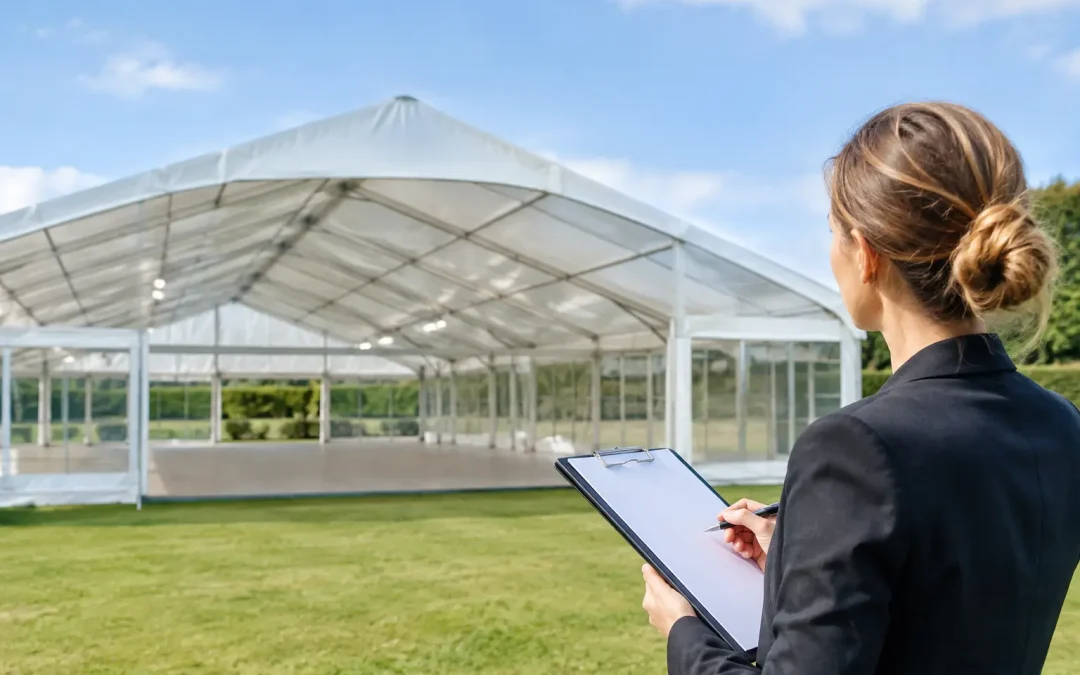
A large temporary structure may only stand for a few days, but the exposure around it can begin long before the first lorry reaches site and continue after the last guest has left. This guide to temporary structure insurance is designed for organisers, production teams and venue operators managing marquees, temporary halls, hospitality units, exhibition structures and associated event infrastructure.
The central question is not simply whether insurance is in place. It is whether every party understands what is insured, who carries which risk, and how the cover works in the conditions actually expected on site. For a public-facing event, gaps often appear at the handover points: between the structure supplier and organiser, between the venue and promoter, or between planned activity and a last-minute operational change.
Start with responsibility, not the policy schedule
Temporary structures involve several parties with overlapping duties. The supplier may own, transport, install and dismantle the structure. The organiser may control the event operation, guest activity and site schedule. A venue, landowner or local authority may impose conditions around access, ground protection, public safety and reinstatement. Contractors can bring power distribution, heating, lighting, furniture, catering equipment, staging and branding into the footprint.
Insurance should reflect these responsibilities rather than assume that one policy covers the whole project. A structure supplier will normally insure its own equipment and maintain public liability cover for its work. That does not automatically protect an organiser against their own liabilities, such as injury arising from crowd management, damage caused by a contractor they have appointed, or losses connected with event cancellation.
Before work begins, establish the contractual position in plain language. Confirm who is responsible for accidental damage to the hired structure, when responsibility transfers, whether the organiser is liable for theft or malicious damage, and what happens if the structure cannot be accessed for collection at the agreed time. These points should match the hire agreement, insurance arrangements and operational plan.
The cover most event projects need to consider
There is no single policy called temporary structure insurance that suits every event. The right mix depends on the scale of the installation, the public profile of the event, site conditions, the value of hired equipment and the commercial consequences of disruption.
Public liability and employer’s liability
Public liability insurance addresses legal liability for injury to third parties or damage to third-party property. For an organiser, this can include attendees, visitors, neighbouring landowners and members of the public affected by event operations. Limits of indemnity should be checked against venue requirements, licence conditions and the scale of potential exposure. Major events and public-sector sites commonly specify minimum limits.
Employer’s liability insurance is required for most businesses employing staff and is relevant where employees, casual workers or crew are working on site. The detail depends on employment status and business arrangements, so organisers should take advice where freelance, volunteer or labour-only teams are involved.
These policies are not a substitute for proper planning. Insurers will expect reasonable controls around vehicle movements, fire safety, crowd routes, emergency access and safe working practices. A policy may respond to an incident, but it cannot repair a poorly managed build programme or protect an event’s reputation in the moment.
Hired-in equipment and structure damage
A marquee or temporary structure can represent a substantial asset, particularly where it includes specialist flooring, clear-span frames, linings, doors, glazing, internal fit-out and bespoke branding. The supplier’s own insurance protects their interest, but hire terms may make the customer responsible for certain losses or damage while the equipment is in their care.
Check whether the organiser’s policy includes hired-in plant or hired equipment, and whether it expressly accommodates temporary structures. Do not assume that a general event policy covers a high-value hired marquee, its contents or equipment left inside overnight. Excesses, sub-limits and exclusions can materially affect the position.
Particular attention is needed where the structure remains open or partially accessible outside event hours. Overnight security, controlled keys, fencing, security patrols and weather monitoring may be conditions of hire or factors an insurer will consider after a claim.
Event cancellation and abandonment
Cancellation insurance is often considered only when tickets are being sold, but the financial exposure can be just as significant for corporate hospitality, agricultural shows, city-centre activations and broadcast projects. A severe weather event, restricted site access, supplier failure, transport disruption or an official restriction can create costs before the public even arrives.
The wording matters greatly. Event cancellation policies may cover specified perils, but they are not a blanket guarantee against poor attendance, a change of commercial preference or every adverse weather forecast. Conditions may require timely notification, documented mitigation efforts and clear evidence of financial loss. If a structure has been ordered well in advance, review cancellation terms before committing to non-refundable production costs.
Property, contents and business interruption
The temporary structure is only one part of the working environment. Bars, catering equipment, AV, stock, furniture, IT equipment, generators and client displays may all require separate consideration. A policy covering permanent business premises may have limited protection for equipment at a temporary event location.
Business interruption cover may also be relevant where an incident affects trading or contractual delivery. It is more commonly associated with permanent premises, so event organisers should not assume it extends to a short-term installation without specific confirmation.
Site conditions can change the insurance conversation
Insurers and underwriters assess risk through the facts of the project. A level, private site with controlled access presents a different profile from an exposed field, a historic estate, a city-centre square or a working industrial yard. Ground conditions, drainage, overhead services, underground utilities, high winds, public routes and restricted vehicle access all influence the practical controls required.
Wind is a particular example. A temporary structure should be designed, installed and managed for the expected site conditions, with suitable anchoring or ballast, documented checks and a clear plan for forecast deterioration. However, weather-related cover may contain exclusions, conditions or definitions that differ from the operational wind limits set by the structure provider. The event team needs both: an insurance response for insured loss and a safe, pre-agreed decision-making process for pausing activity, evacuating or closing the structure.
Changes made after the original design can introduce avoidable risk. Adding heavy signs, drapes, lighting, heating equipment or suspended production elements without approval can affect loading, fire precautions and liability. Any material change to the structure’s use or layout should be reviewed by the relevant suppliers and recorded in the event documentation.
Documents that support a defensible project
When a claim occurs, the quality of records can be as important as the quality of the policy. Event teams should be able to show what was agreed, what was built and how risks were managed during live operation.
For complex projects, keep a controlled set of documents covering the following:
- hire terms, responsibilities and insurance requirements for each party;
- certificates of insurance from suppliers and contractors, checked for appropriate limits and dates;
- structure plans, build records, handover information and inspection arrangements;
- risk assessments, method statements, fire plans, traffic management and emergency procedures;
- photographs of site condition, access routes and the completed installation; and
- incident logs, weather records and records of any decisions to alter operations.
This is not paperwork for its own sake. It gives the event manager a clear operational baseline and prevents uncertainty when staff change, site conditions shift or a concern is raised during an inspection.
Avoid the common gaps between supplier and organiser
The most frequent misunderstanding is believing that the marquee supplier’s insurance fully transfers to the client. It does not. The supplier is responsible for their operations and assets under the agreed terms, while the organiser remains accountable for their own event activity and contractual commitments.
Another gap appears when several contractors work inside one structure. A catering contractor may bring cooking equipment, a production company may rig lighting, and a client may install displays or furniture. Each activity has its own risk profile. The organiser should ensure that approvals, certificates, fire controls and insurance evidence are coordinated rather than collected in isolation.
Finally, consider the end of the event. Delayed access, vehicle damage to soft ground, waste left in the structure, unauthorised overnight use and late removal of client equipment can all create disputes after guests have gone home. The de-rig plan should set out who controls the area, when the supplier can return, and what remains the organiser’s responsibility until collection is complete.
Make insurance part of the build plan
Insurance works best when it is considered at the same point as site surveys, layout design and contractor appointment. For large or complex installations, involve the structure supplier early enough to identify practical controls around access, anchoring, ground protection, emergency routes and build sequencing. At Purvis Marquee Hire, that operational detail is treated as part of delivering a safe, workable temporary environment, not an afterthought once the structure is standing.
The useful outcome is not simply a folder of certificates. It is a project team that knows where responsibility sits, can evidence sensible decisions, and has a clear route to act if site conditions or the event plan change.